

Get Paid Early: Cash Advance

- 167.00 Reviews
- 4.2
- Downloads
- 50,000+
Our take on Get Paid Early: Cash Advance from Appgk
I approached Get Paid Early: Cash Advance as a practical finance app rather than a general budgeting tool. Its purpose is straightforward: help eligible users access earned pay before the normal payday, without presenting the service as a conventional loan. That distinction matters, because the useful question is not whether early access sounds convenient, but whether it fits the way you already manage income, bills, and timing.
In my experience, the app makes the most sense for someone who occasionally has a gap between an unavoidable expense and the next paycheck. A utility bill, a necessary trip, or a grocery purchase can arrive at an awkward point in the pay cycle. Instead of turning to a credit card or a traditional short-term loan, a user may prefer to explore an earned-pay option. I would still treat it as a cash-flow tool, not extra income. It can move money forward, but it cannot improve the overall balance of a budget.
How the current app fits into everyday money management
StreamFunds, Inc. develops this free finance app, and its central appeal is the promise of earlier access to pay that has already been earned. The store positioning emphasizes no loans, no interest, and no hidden fees, which gives the product a noticeably different starting point from payday lending. That does not mean every user will have the same experience or that early access removes the need to understand the repayment timing. I would read the available terms carefully before relying on it for a recurring expense.
The app is aimed at a broad audience, with an Everyone content rating and support beginning with Android 7.0. That makes it accessible on many older Android devices, although compatibility alone does not tell you whether the service will suit your employment or payroll situation. The important practical issue is whether your earned wages can be recognized through the setup process. A user should approach installation with realistic expectations: the app is designed around access to earned pay, not around building a long-term spending plan.
Best Parts of Get Paid Early: Cash Advance
Things to Keep in Mind About Get Paid Early: Cash Advance
The current release is version 3.0.39, and the product has been available since March 25, 2026. Those details suggest a relatively current app experience rather than a forgotten utility, but a version number is not a guarantee that every workflow will feel polished on every phone. I pay attention to whether an app makes the first important action clear, whether it explains timing in plain language, and whether it helps me avoid confusing available pay with disposable money.
Its public reception is reasonably encouraging. The app holds a 4.2 average from around seven hundred ratings, with more than one hundred written reviews and over fifty thousand installs. I see that as enough adoption to show genuine interest, while still being a smaller footprint than the biggest finance platforms. In practical terms, I would expect a more focused experience than a full banking suite, and I would not choose it expecting investment tools, detailed credit monitoring, or comprehensive household accounting.
News and Features Related to Get Paid Early: Cash Advance

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The first setup deserves more attention than it usually gets
When I try an earned-pay service, I do not rush through the opening screens simply to reach the withdrawal option. The most important early task is understanding what information the app needs to determine eligibility and how it connects access to a user’s pay cycle. Even when a service is free, I want to know what I am authorizing, when the money is expected to arrive, and how the next paycheck will be affected.
A useful habit is to install the app before an emergency occurs. That gives you time to review the account flow, check whether your employment details are recognized, and understand the available choices without the pressure of a bill due that afternoon. This is one of the less obvious strengths of planning ahead: the app can be evaluated calmly, instead of becoming a rushed substitute for a broader emergency fund.
Don't want to read the full review?
I would also keep notifications enabled if the app uses them to communicate status or timing, but I would not treat a notification as a replacement for checking my bank account. Early-pay products depend on timing, and weekends, payroll processing, or account details can affect when money is actually usable. A careful user confirms the result in their bank before scheduling a payment that cannot be missed.
What the newer release tells existing users
For current users, version 3.0.39 is the clearest marker of the app’s present state. The release date gives the product a defined point in its development, but it does not justify assuming that every older account will behave exactly like a new installation. Existing users should update through their normal app store route and then revisit the main access flow, especially if they previously saved account information or relied on a familiar screen arrangement.
Screenshots
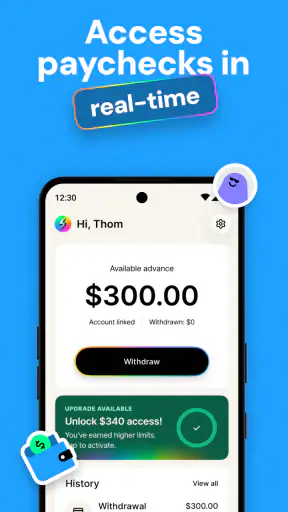
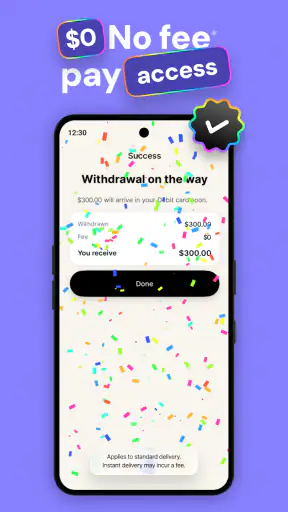
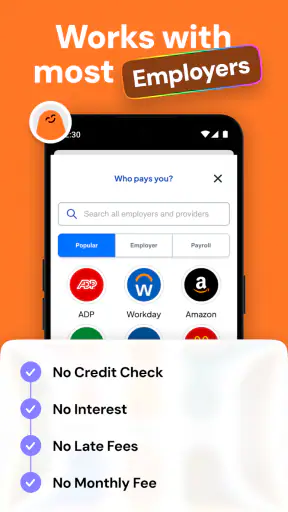
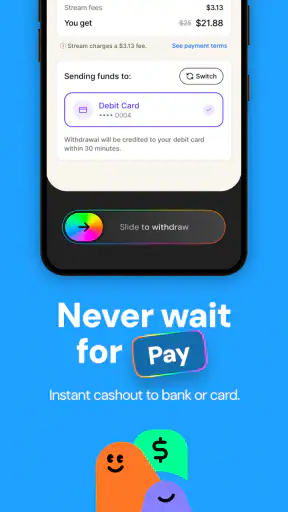
My practical advice after an update is simple: open the app when you have a few quiet minutes, check the displayed pay information, and review any prompts before requesting money. A changed button location is a minor inconvenience; a misunderstood timing message can create a real problem. I would not make a first post-update request immediately before rent, a subscription renewal, or another payment with no flexibility.
The evolution from earlier versions to the current release is most useful when viewed as maintenance of a financial workflow, not as a reason to borrow more often. A newer build may make navigation or account handling more comfortable, but it does not change the basic trade-off: receiving earned pay sooner means planning around the amount that will remain available later. That is the point existing users should keep in focus, regardless of interface improvements.
Someone who already uses the service may notice the greatest benefit during irregular weeks. If a paycheck normally arrives after a recurring bill, early access can reduce the temptation to carry a balance on a credit card. However, if every pay period requires an advance, the feature is no longer functioning as occasional support; it is masking a permanent mismatch between income and expenses. In that situation, I would pair the app with a written spending plan and look for a more sustainable adjustment.
A realistic use case: solving a timing problem without expanding it
Imagine that I have worked enough hours to earn part of my paycheck, but a necessary household expense appears several days before payday. I open the app, review the amount that can be accessed, and compare it with the exact bill rather than taking the largest available amount automatically. If the expense is modest, requesting only what I need can reduce the pressure on the next paycheck. That small decision is more important than it sounds, because convenience can encourage overuse.
After receiving the money, I would record it in my regular budget as pay already brought forward. I would not list it as a bonus, windfall, or new source of income. On the following payday, I would check that the remaining amount covers planned essentials. This two-step habit—deciding the amount before requesting and then adjusting the next-payday budget—turns the app into a controlled timing tool instead of an impulse-spending shortcut.
The same approach helps answer a common question: is this better than using a credit card? It can be, when the alternative would be interest-bearing debt and the expense is genuinely necessary. But a credit card may offer protections or flexibility that an earned-pay service does not, while a savings account is usually the cleaner option if the money is already available. I would compare the actual cost, timing, and consequences rather than assuming that “early” automatically means “better.”
Where it compares well with ordinary alternatives
Compared with a conventional short-term loan, the app’s main appeal is its earned-pay framing. A loan creates a new obligation based on borrowed money; this service is presented as access to wages already earned. That difference may make it easier for a user to avoid interest-based borrowing. Still, both choices can affect future cash flow, so I would focus on the repayment impact rather than the label alone.
Compared with a bank overdraft, the app may feel more deliberate because the user chooses to access pay before the normal deposit. An overdraft often happens after a payment has already been attempted, which can make the situation harder to control. On the other hand, people with a dependable emergency fund do not need either option for routine surprises. Savings preserve the full future paycheck and do not turn a timing issue into a repeated cycle.
Compared with a broad budgeting app, this product is narrower. A budgeting app can help categorize spending, plan bills, and show patterns over time; Get Paid Early: Cash Advance focuses on the immediate relationship between earned pay and access. I would use it when the urgent problem is timing, not when I need to understand why my monthly spending keeps exceeding income. In some households, the best combination may be a budget tool for planning and this app only as an occasional backup.
Small workflow choices that make a meaningful difference
My first tip is to calculate the exact shortfall before opening the request screen. If a bill is lower than the amount offered, taking extra money weakens the purpose of early access. Write down the expense, the amount already in the bank, and the next payday’s unavoidable commitments. This simple check can prevent a convenience feature from becoming a source of discretionary spending.
My second tip is to create a “next paycheck” view in whatever budgeting method you already use. Put the expected remaining income at the top, then subtract rent, transportation, food, and automatic payments. The app can help with the immediate gap, but your own calculation shows whether the gap is temporary or structural. If the result is negative even after the advance, the app is not solving the real problem.
My third tip is to test the process with a low-stakes situation before depending on it for an urgent payment. This lets you learn how the app presents eligibility, timing, and account status without making your first experience occur under pressure. It also answers a question many new users have: will the workflow feel understandable on my particular device and with my pay schedule? Discovering friction early is far better than discovering it beside a payment deadline.
A fourth useful practice is to keep a record of every early-access decision. I would note the date, amount, reason, and effect on the following payday. After a few pay cycles, the pattern becomes visible. If the requests are rare and tied to genuine timing problems, the app may be serving its intended role. If they appear after ordinary shopping or every payday, that is a warning to stop and reassess spending.
The gaps and situations where I would skip it
The biggest limitation is that early access can make a tight budget look healthier for a short time. The bill gets paid, but the next paycheck arrives with less room. Users who already struggle to track automatic payments may find this especially risky. I would skip the app if I could not explain, in advance, how the following payday would cover essentials.
I would also choose another solution when the need is large, ongoing, or connected to a long-term financial problem. An earned-pay app is not a replacement for negotiating a bill, increasing income, reducing fixed costs, or speaking with a qualified financial counselor. If the same expense keeps forcing an advance, repeating the transaction may postpone the decision that actually needs to be made.
Another reason to hesitate is uncertainty around eligibility or timing in a particular employment arrangement. The product’s purpose depends on recognizing earned pay, so a user should not assume that having a smartphone and a paycheck automatically guarantees smooth access. If the setup does not clearly match your work situation, I would avoid building an urgent payment plan around it.
Privacy and account security deserve ordinary caution as well. I would use a strong device passcode, keep the operating system current, and review each permission or connection request instead of approving everything automatically. Those habits are not unique to finance apps, but they matter more when an app is involved in income and bank-related activity. Convenience should never mean abandoning basic account hygiene.
Questions I would answer before installing
Is the app genuinely free to download? Yes, it is listed as free. That answers the installation question, but I would still read the in-app explanation of any transaction, optional service, or timing condition before proceeding. “Free” should not be interpreted as “no decision is required.” The responsible step is understanding the specific flow offered to your account.
Can anyone use it immediately? I would not assume that. The app is built around earned pay, so the relevant question is whether your work and payroll circumstances can be supported during setup. Install it early, complete the checks carefully, and do not promise a bill payment until you know the app can actually serve your situation.
Will it replace a bank account or a budgeting app? I would not use it that way. Its value is concentrated in accessing earned wages earlier, while a bank account handles deposits and payments and a budgeting app handles planning. If you want spending categories, savings goals, or a complete financial overview, you will likely need a separate tool or a more comprehensive service.
Does using it mean I have more money? No. It changes when part of your pay becomes available, not how much you earn. That is the most important mental safeguard. I would only request an amount that I can explain as a necessary timing adjustment and that I have already considered in the next payday’s budget.
Who should avoid it? I would steer clear if you are looking for long-term debt relief, if you cannot track upcoming bills, or if you are tempted to use early access for routine wants. Someone with savings available for the expense should generally use that buffer first, because it avoids reducing the next paycheck. The app is best suited to a narrow, temporary cash-flow problem.
What I would watch as the product continues
For future use, I would watch how clearly the app communicates eligibility, access timing, and the effect on the next payday. Those explanations matter more than decorative interface changes. A finance app earns trust when a user can understand the consequence of an action before tapping it, especially during a stressful week.
I would also pay attention to whether the current version remains comfortable for existing users on older supported Android devices. Support beginning with Android 7.0 broadens reach, but real usability depends on readable screens, stable navigation, and clear status messages across different phones. A focused service does not need dozens of features; it does need a dependable core workflow.
My overall view is positive but measured. Get Paid Early: Cash Advance is a useful option for a person facing a genuine payday mismatch and wanting to consider earned-pay access before a loan or overdraft. Its limited scope is also its boundary: it does not replace savings, budgeting, or a plan for recurring deficits. I would recommend trying it ahead of an emergency, requesting only the amount that solves the specific problem, and checking the next paycheck before committing to anything. Used with that discipline, this free finance app can be a practical buffer; used casually, it can simply move the same money problem a few days forward.
Get Paid Early: Cash Advance FAQ
What is Get Paid Early: Cash Advance, and how does it work?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected income before their regular payday. After creating an account and completing the required verification, the app may review information such as employment, income, and banking activity to determine eligibility. Approved users can request an advance, review the applicable fees or optional costs, and receive funds through the available delivery method.
Who can use Get Paid Early: Cash Advance?
Availability depends on factors such as your age, location, employment status, income, identity verification, and connection to a qualifying bank account or payroll provider. Meeting the basic requirements does not necessarily guarantee approval, because eligibility can also depend on the app’s current risk assessment. Before applying, review the latest requirements, supported regions, repayment terms, and disclosures shown inside the app.
How much money can I borrow, and when will I receive it?
The advance amount is generally based on your verified income, account history, repayment capacity, and other eligibility information. New users may receive a smaller limit, while limits can change over time. Standard transfers may take longer, whereas an expedited option may be available for an additional charge. The exact amount, estimated arrival time, and total cost should be confirmed before accepting an advance.
Are there fees, interest, or other costs involved?
Cash advance services can involve several types of costs, including subscription charges, express-transfer fees, optional tips, or other service fees. The total cost may vary depending on the amount requested and the delivery method selected. Carefully read the fee summary and repayment information before confirming a transaction. Do not assume that an advance is free simply because it is described as having no traditional interest.
How is repayment handled, and is Get Paid Early: Cash Advance safe to use?
Repayment is typically scheduled automatically from a linked bank account or another approved payment source on the date displayed in the agreement. Make sure sufficient funds are available to avoid failed payments, overdraft charges, or account restrictions. The app may use encryption and identity-verification measures, but users should still review permissions, privacy practices, lender or provider disclosures, and customer-support options before sharing financial information.











